Bike and scooter loans in Nepal: down payment, interest and EMI on Rs 2–5 lakh
Wheels of Nepal · Last updated: · 9 min read
To finance a bike or scooter in Nepal you must normally pay at least 40% yourself, because lenders licensed by Nepal Rastra Bank can lend at most 60% on a private vehicle. On a Rs 3 lakh motorcycle that means about Rs 1.2 lakh down, and in our worked example an EMI of roughly Rs 5,700 a month over three years at the 8.99% rate Bajaj's finance partner published in July 2026.
Two-wheeler finance in Nepal works a little differently from car loans. Most buyers sign up at the showroom with a hire-purchase company that partners the distributor, rather than walking into a bank. This guide explains the rules that apply either way, the rates that have actually been published, and what the monthly instalment (EMI) looks like across the Rs 2–5 lakh range. For car loans, see our separate auto loan guide.
How much do you have to put down?
Nepal Rastra Bank (NRB) caps the loan-to-value ratio for private vehicles at 60%, whether petrol or electric. NRB set this single cap in the mid-term review of its FY 2024/25 monetary policy, as Business 360 reported in February 2025. We found no separate, higher limit for motorcycles or scooters.
So for a bank or an NRB-regulated finance company, the minimum down payment is 40% of the vehicle price. Banks apply the 60% to the dealer quotation; Nepal Bank's auto loan page, for example, says it lends up to 60% of the quotation price or as NRB directives allow.
Some showroom offers advertise much smaller "starting" payments. Before you sign, ask the lender in writing how much of the price it is financing, what the rest of the cost is made up of, and whether the plan is a loan, a hire-purchase agreement or a credit-card instalment plan. They are not the same product.
Who lends on two-wheelers?
Hire-purchase companies at the showroom
The big distributors work with hire-purchase partners:
- Bajaj: HH Bajaj, the official distributor, finances through Hulas Finserv Hire Purchase Ltd., which The Himalayan Times describes as regulated by NRB. In July 2026 the two cut the rate from 9.99% to 8.99% and extended the maximum term from 36 to 60 months, across the whole Bajaj motorcycle range.
- Honda: Honda Nepal names Syakar Hire Purchase Pvt. Ltd. as its finance partner. Its financing page lists the papers needed but does not publish a rate or down payment. Honda's October 2026 festive offer mentions finance "at a low interest rate" without figures.
Other brands run their own schemes from time to time. Rates and terms change with each campaign, so treat any advertised figure as valid only for the dates stated.
Banks
Banks publish auto loan rates, but they are written mainly for cars. Nepal Bank's rate sheet effective Kartik 1, 2083, for example, lists a fixed auto loan at 7.99% for 5 years and an EV loan at 7.90% for 5 years, but has no row for two-wheelers, and its auto loan page does not say whether motorcycles qualify. If you would rather borrow from your own bank, ask whether it finances two-wheelers at all, and at which rate, before you book.
| Route | Who | What is published |
|---|---|---|
| Showroom hire purchase | Distributor's finance partner (e.g. Hulas Finserv for Bajaj, Syakar for Honda) | Bajaj: 8.99%, up to 60 months. Honda: documents only |
| Bank auto loan | Commercial banks | Car-focused rate sheets; two-wheeler eligibility not stated by the bank we checked |
Flat or reducing rate: ask which
An interest rate can be charged in two ways:
- Reducing balance: interest is charged only on what you still owe, so it falls every month. Bank loans and the EMI formula below work this way.
- Flat rate: interest is charged on the original loan for the whole term. A flat rate of the same number costs noticeably more.
The Bajaj announcements do not say which method the 8.99% uses. Ask the lender to write the method and the total amount you will repay on the agreement.
EMI examples from Rs 2 lakh to Rs 5 lakh
These are our examples for illustration. Assumptions: the indicative ex-showroom price on the official site (checked October 2026), a 60% loan and a 40% down payment, and a reducing-balance rate of 8.99% (the published Bajaj–Hulas rate) or 12% (our assumption for a costlier lender). We used the standard formula EMI = P × r × (1 + r)ⁿ ÷ ((1 + r)ⁿ − 1), where r is the monthly rate and n the number of months. Fees are not included.
| Vehicle (official price) | Down payment (40%) | Loan (60%) | EMI, 24 months at 8.99% | EMI, 36 months at 8.99% | EMI, 60 months at 8.99% |
|---|---|---|---|---|---|
| Hero Splendor+ Rs 2,17,900 | Rs 87,160 | Rs 1,30,740 | Rs 5,972 | Rs 4,157 | Rs 2,713 |
| Honda Shine 125 DRS Rs 2,99,900 | Rs 1,19,960 | Rs 1,79,940 | Rs 8,220 | Rs 5,721 | Rs 3,734 |
| Ather Rizta Base Rs 3,19,900 | Rs 1,27,960 | Rs 1,91,940 | Rs 8,768 | Rs 6,103 | Rs 3,983 |
| Bajaj Pulsar N160 Rs 4,47,900 | Rs 1,79,160 | Rs 2,68,740 | Rs 12,276 | Rs 8,545 | Rs 5,577 |
| Royal Enfield Hunter 350 Rs 4,87,000 | Rs 1,94,800 | Rs 2,92,200 | Rs 13,348 | Rs 9,291 | Rs 6,064 |
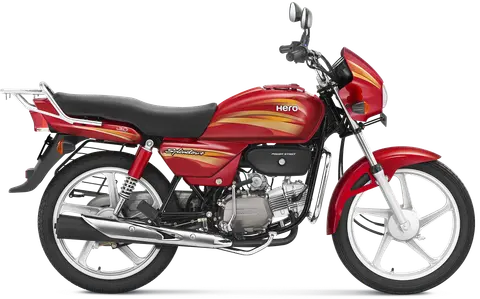 Hero Splendor+Rs 2,17,900
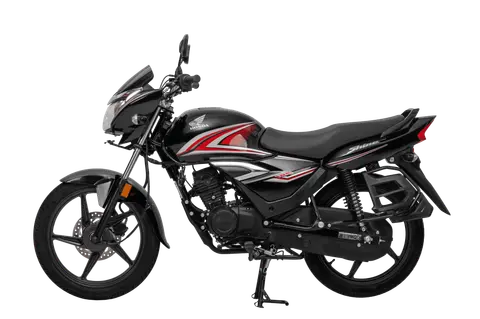 Honda Shine 125Rs 2,99,900 – Rs 3,09,900
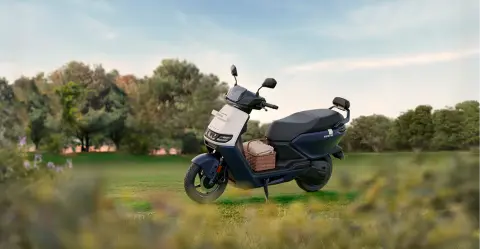 Ather RiztaRs 3,19,900 – Rs 4,19,900
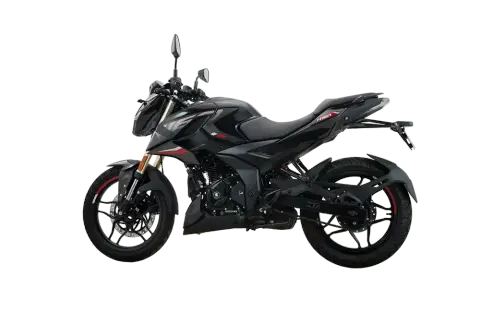 Bajaj Pulsar N160Rs 4,47,900
 Royal Enfield Hunter 350Rs 4.87 lakh – Rs 5.11 lakh
What a longer term really costs
A longer term lowers the EMI but adds interest. On the Honda Shine 125 loan of Rs 1,79,940:
- 24 months at 8.99%: total interest about Rs 17,330
- 36 months at 8.99%: about Rs 26,020
- 60 months at 8.99%: about Rs 44,120
- 60 months at 12% (assumed): about Rs 60,220
| 24 months, 8.99% | 17,332 Rs |
|---|---|
| 36 months, 8.99% | 26,023 Rs |
| 60 months, 8.99% | 44,123 Rs |
| 60 months, 12% (assumed) | 60,220 Rs |
Source: Our worked example: Honda Shine 125 DRS at Rs 2,99,900 (official price, Oct 2026), 60% loan, reducing balance; 8.99% is the published Bajaj–Hulas rate, 12% is an assumption
Stretching from three years to five cuts this EMI by about Rs 2,000 a month but costs about Rs 18,000 more in interest. On a commuter bike that will be worth much less in five years, a shorter term is usually the better deal if you can manage the EMI.
Why showroom EMIs may look lower
Bajaj's published examples are lower than ours: about Rs 2,124 a month over 60 months for the Platina 100 ES. For comparison, a 60% loan on the Platina's official price of Rs 2,61,900 at 8.99% over 60 months works out at about Rs 3,260 in our arithmetic. The announcement does not state the loan amount or down payment behind its figure, so a larger down payment is the likely difference. Ask the showroom for the exact loan amount behind any advertised EMI.
To run your own numbers, use our EMI calculator. It starts at a 40% down payment.
The cash you need on day one
The loan covers only part of the price. You will also pay, at or soon after delivery:
| Item | Amount | Source |
|---|---|---|
| Down payment | At least 40% of the price | NRB 60% cap |
| Embossed number plate | Rs 2,500 for a motorcycle or scooter | DoTM fee, Kathmandu Post |
| Third-party insurance (compulsory) | Rs 1,500 below 150cc, Rs 1,700 for 150–250cc, Rs 1,900 above 250cc, before VAT and stamp duty | Current tariff, Bizmandu; a revision is pending |
| Annual vehicle tax, up to 125cc | Rs 2,700 to Rs 3,100 depending on province | Ratopati, FY 2083/84 |
| Registration fee | Not published in any source we could check | Ask the dealer |
Lenders usually also want the vehicle insured for its full value until the loan is repaid, so ask for a comprehensive insurance quote. For the yearly costs, see our guide to road tax and insurance, and see registering a new vehicle for the steps after you pay.
Documents you will usually need
Honda Nepal's financing page and HH Bajaj's loan page list similar papers:
- Citizenship certificate (copies) and passport-size photos
- Proof of income: salary certificate, business registration and tax papers, pension book, foreign-income papers, or bank statements (Honda's partner asks for 12 months)
- A personal guarantor, usually a family member, with their own photos and ID
- A CIB report (credit check) and a driving licence (Honda's partner lists both)
- Address proof, such as a recent water or electricity bill for the guarantor
HH Bajaj says applicants are generally aged 18 to 65 at the end of the loan.
Checklist before you sign
- Ask for the rate method (flat or reducing) and the total repayable in writing.
- Ask for every fee: processing, documentation, late payment and early settlement.
- Check the loan amount behind any advertised EMI.
- Compare two quotes: the showroom's partner and your own bank.
- Keep the EMI comfortable. Leave room for fuel or charging, tax, insurance and servicing. If you are choosing between petrol and electric, see petrol vs electric two-wheelers.
- Get the release letter when the loan is paid off, and have the lender's name cleared from the bluebook. You will need this to sell.
Still choosing? Browse the bike price list, the scooter price in Nepal list or the best scooters under Rs 3 lakh.
Sources
- Business 360 – Monetary policy mid-term review: vehicle loan ratio set at 60% (26 February 2025)
- The Himalayan Times – Bajaj rolls out lower-EMI financing scheme, extends loan tenure to five years (20 July 2026)
- Business 360 – HH Bajaj launches five-year financing scheme with Hulas Finserv, cuts interest to 8.99% (19 July 2026)
- HH Bajaj (official Bajaj distributor) – Bajaj bike EMI from Rs 2,124 a month: tenure, documents and eligibility (16 July 2026)
- Honda Nepal (Syakar) – Financing facilities: finance partner and documents
- Honda Nepal – Dashain offer on bikes and scooters (2 October 2026)
- HH Bajaj – Platina 100 ES official price
- Official Nepal prices via our catalogue – Hero (Splendor+), Honda (Shine 125), Ather (Rizta), HH Bajaj (Pulsar N160), Royal Enfield (Hunter 350)
- Nepal Bank Limited – Auto loan: eligibility, documents, tenure and LTV
- Nepal Bank Limited – Interest rates (effective Kartik 1, 2083)
- The Kathmandu Post – Government pushes ahead with embossed number plates (26 August 2025)
- Bizmandu – Third-party motor insurance liability doubled; premiums under revision (8 July 2026)
- Ratopati – In which province is the annual vehicle tax cheaper? (3 Shrawan 2083, FY 2083/84 rates)
#bike-loan#scooter-loan#emi#hire-purchase#two-wheeler#nrb#buying-guide